Drunk-dialling is generally a bad idea. It might mean calling a crush and professing your undying love, or maybe calling your boss and leaving a rambling 20-minute message about how much you hate your job.
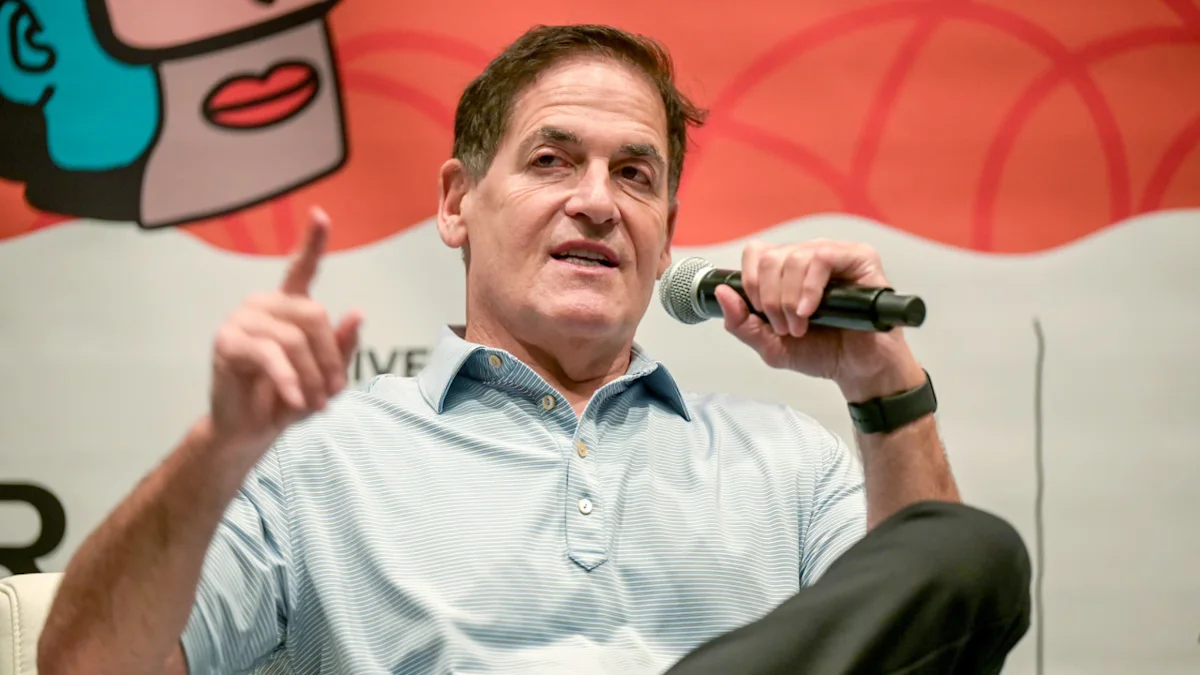
In 1990, when entrepreneur and investor Mark Cuban was 32, he drunk dialled American Airlines after selling his first startup, MicroSolutions, for $6 million.
Must Read
“My buddies and I went out and just got destroyed,” he told the Club Shay Shay podcast back in 2024. “They’re like, ‘What do you think you’re going to do with all this money?’ And I’m like, ‘I don’t care about cars or houses, but boy, you know, I fly a lot for work.'”
He ended up spending $125,000 on an AAirpass, a lifetime pass that guaranteed him a first-class seat on any American Airlines flight for the rest of his life. Worth noting, the airline halted memberships in 2022 and sunsetted the program in 2024.
That didn’t affect Cuban, though. Back in 1999 he splurged on a $40 million private jet after selling his Broadcast.com streaming platform to Yahoo for $5.7 billion in stock.
The ‘rule’ of splurging
While your odds of winning the lottery are slim, there are other ways you might find yourself on the receiving end of a large sum of cash: a work bonus, an inheritance, a life insurance payout or the sale of a business.
If you receive a financial windfall, especially one that’s unexpected, it can be tempting to go out and splurge on a big-ticket item like a sports car or luxury vacation. And that’s okay, if the math adds up.
One common rule of thumb that can help you manage a windfall is to set aside 5% for guilt-free spending. That means if your windfall is $10,000, you’d have $500 for splurging, while a $100,000 windfall would leave you with $5,000 in fun money.
For example, Cuban’s $125,000 splurge was less than 5% of the total sale of MicroSolutions (which would be $300,000). But, after taxes, he actually only took home about $2 million, so he would have had about $100K for splurge money, if he were following the 5% rule of thumb.
Even though he was drunk dialling, Cuban did a few things right. His splurge wasn’t on a depreciating asset, like a sports car (a new car depreciates as soon as you drive it off the lot, losing about 30% of its value over the first two years).
Plus, with a flight pass, he wasn’t paying maintenance fees, property taxes or insurance — like he might with other big-ticket purchases.
He also hedged against future travel inflation. While American Airlines no longer offers the AAirpass, that pass would be worth about $300,000 today (when adjusted for inflation).
Cuban also invested in himself, since he had access to business flights whenever he needed them. At the time, the pass would guarantee you a seat, even if the flight was full (meaning someone else would get bumped off). That buys a lot of freedom.
Read More: Vanguard reveals what’s coming for U.S. stocks — and it could be bad news for this group of investors
What to do with a financial windfall
Almost one in three Americans (31%) who received or expected a windfall would go shopping, according to a June 2026 survey by Empower, while 12% would make a major purchase such as a car or home renos.
The best thing to do? Wait. A sudden influx of cash can be exciting, but also overwhelming. And you could quickly whittle away that windfall through splurges, gifts to friends or even lifestyle inflation (spending more as your income increases).
Cuban, for example, may have purchased a private jet as a splurge, but he’s also been living in the same house since 1999 (albeit a mansion in Dallas), drives practical cars and even buys in bulk.
Plus, you may not get to keep the full amount of the windfall.
For example, life insurance payouts typically aren’t taxed, but some inheritances are taxed at the state level by up to 16% (though there are no federal inheritance taxes). If you sell a business, you’ll have to account for state and federal income taxes.
Inheriting a retirement savings account like a 401(k) or traditional individual retirement account (IRA) means you’ll have to take distributions, usually within 10 years (unless you’re the surviving spouse or otherwise exempted). Those distributions are taxed as ordinary income, which could actually increase your tax bill if it bumps you up into a higher tax bracket.
That’s why waiting at least six months before making any major purchases can help you avoid missteps — so, try to avoid drunk dialling before buying a big-ticket item.
Once you figure out how much money you’ll receive after taxes, consider paying down high-interest debt, increasing your emergency fund to cover at least three to six months of expenses and then allotting the rest to savings and investments. Maybe that means funding a long-term goal, like a down payment for a house, or contributing more to your retirement savings.
If you plan on gifting some of that money to friends or family, keep in mind that you can gift up to $19,000 to an individual in 2026 — after that, it counts toward your lifetime gift tax exclusion (and requires filing a federal gift tax return).
Being intentional about what you do with a financial windfall can help ensure that your money will keep on giving (ideally, in the form of compounding interest) and you don’t end up with depreciating assets you don’t want down the road.
If you’re unsure of what to do, it can help to talk to a qualified financial advisor or estate planning attorney.
What To Read Next
Get Warren Buffett’s best investing lessons, free. Join 250,000 readers getting Moneywise’s sharpest money reporting every week. Subscribe and we’ll send you our guide to the ideas that built Buffett’s fortune as a welcome gift.
This article originally appeared on Moneywise.com under the title: Mark Cuban spent $125,000 on a lifetime American Airlines pass after a drunk dial — here’s why the math worked
This article provides information only and should not be construed as advice. It is provided without warranty of any kind.